A car accident can change your life in seconds. You may be juggling medical appointments, missed work, car repairs, and calls from multiple insurance adjusters—often while you are still in pain.
Why Car Crash Injury Claims Feel Overwhelming
This guide offers a practical, step‑by‑step checklist for handling a U.S. car accident injury claim. It is general information, not legal advice. For guidance about your specific situation, speak with a licensed attorney in your state.
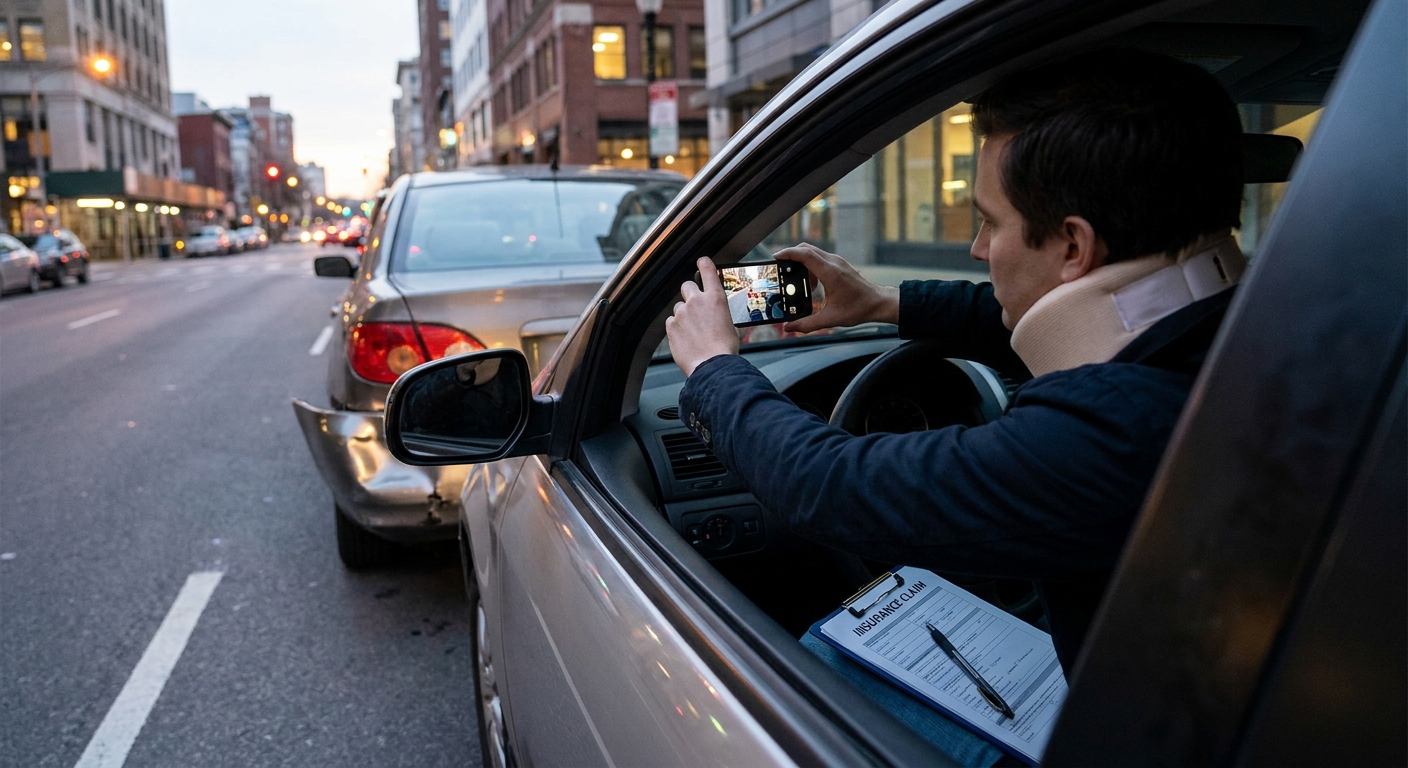
Step 1: Safety and Documentation at the Scene
If you are able to move safely:
Immediate Actions
- [ ] Move to a safe location if possible and turn on hazard lights.
- [ ] Call 911 and request police and medical assistance if anyone is injured.
- [ ] Exchange information with all drivers:
- Names, addresses, phone numbers
- Driver’s license numbers
- License plate numbers
- Insurance companies and policy numbers
- [ ] Obtain contact details for any witnesses.
- [ ] Take photos and videos:
- Vehicle positions and damage
- Skid marks, debris, traffic signals
- Visible injuries
- Weather and road conditions
If police respond, ask how to obtain a copy of the accident report.
Step 2: Get Medical Care—Even If You Feel “Fine”
Car crashes often cause injuries that worsen over time: whiplash, concussions, soft‑tissue damage, internal injuries. Adrenaline can mask pain.
Within 24–48 hours:
- [ ] Visit an ER, urgent care, or your primary doctor.
- [ ] Describe all symptoms, even mild ones (headache, stiffness, dizziness, numbness).
- [ ] Follow doctors’ recommendations for imaging, referrals, and follow‑ups.
Delays in treatment can:
- Put your health at risk.
- Give insurance companies a reason to doubt your injuries are crash‑related.
Step 3: Notify the Right Insurance Companies
You may need to report the crash to:
- Your own auto insurer (often required by your policy).
- The at‑fault driver’s insurer (if known).
- Your health insurer (for medical bills).
When reporting:
- Stick to basic facts: date, time, location, vehicles involved.
- Avoid guessing about fault or minimizing your symptoms.
- If the other insurer asks for a recorded statement, you can say you’ll provide information after you speak with an attorney.
Step 4: Understand the Coverages That May Apply
Depending on your state and your policy, the following may be involved:
1. Liability Coverage (At‑Fault Driver’s Policy)
- Pays for your injuries and property damage if their driver is legally responsible.
- Subject to policy limits—the maximum amount the insurer must pay.
2. Collision Coverage (Your Policy)
- Pays for repairs or replacement of your vehicle, minus your deductible, regardless of fault (in most policies).
3. Medical Payments (MedPay) or Personal Injury Protection (PIP)
- MedPay: Helps cover medical bills, regardless of fault, up to a set amount.
- PIP: In certain “no‑fault” states, covers medical expenses and sometimes lost wages regardless of who caused the crash.
4. Uninsured/Underinsured Motorist Coverage (UM/UIM)
- Applies if the at‑fault driver has no insurance or not enough to cover your losses.
Review your policy, or ask your insurer to explain your coverages in writing.
Step 5: Track All Damages from Day One
To be compensated, you must prove what you lost.
Medical and Health‑Related
- [ ] ER, urgent care, hospital records
- [ ] Bills for doctors, specialists, physical therapy
- [ ] Pharmacy receipts
- [ ] Receipts for medical equipment (braces, crutches, etc.)
Work and Income
- [ ] Employer letter or timesheets showing missed days
- [ ] Pay stubs or tax returns to prove income
- [ ] Notes about reduced hours or changed duties
Vehicle and Property Damage
- [ ] Repair estimates and invoices
- [ ] Towing and storage bills
- [ ] Rental car or rideshare receipts
Daily Life Impact
- [ ] Journal of pain levels and limitations (sleep, hobbies, family activities)
- [ ] Notes about missed events (vacations, sports, caregiving tasks)
Create a dedicated folder or digital drive for this information.
Step 6: Typical Timeline for a Car Accident Injury Claim
While every case is unique, many follow this pattern:
First Week–3 Months
- Emergency and early medical care
- Vehicle repair or total loss settlement
- Initial calls with insurers
3–9 Months
- Ongoing treatment and physical therapy
- Specialist evaluations, diagnostic imaging
- Initial settlement discussions for property damage and minor injuries
9–18+ Months
- Once your treatment stabilizes, your lawyer (or you) may submit a settlement demand.
- Negotiations with insurers
- Potential resolution for many cases with moderate injuries
If a Lawsuit Is Filed
- Discovery, depositions, motions, and possibly trial can extend the case to 1–3+ years total.
Remember: your state’s statute of limitations sets a legal deadline to file a lawsuit. Missing it can bar your claim, so ask an attorney early about your deadline.
Common Insurance Tactics to Watch For
Insurance companies are businesses. Adjusters are often friendly, but their job is to limit payouts.
Be cautious if you encounter:
- Quick, lowball offers before your treatment is finished.
- Requests for broad medical authorizations covering unrelated past conditions.
- Pressure to give a recorded statement immediately.
- Blame shifting—suggesting you were partially at fault without clear evidence.
- Minimizing your pain because diagnostic tests appear “normal.”
You have the right to ask questions, request explanations in writing, and consult an attorney before agreeing to anything.
When It’s Worth Hiring a Car Accident Lawyer
You may be able to handle a very minor property‑damage‑only claim yourself. But speaking with a lawyer is especially important when:
- You have moderate or serious injuries (broken bones, surgery, head injury, ongoing pain).
- You missed more than a few days of work or cannot return to your usual job.
- There is a dispute about who caused the crash.
- Multiple vehicles or a commercial truck are involved.
- You were a pedestrian, cyclist, or motorcyclist hit by a car.
- The at‑fault driver had no insurance or minimal coverage.
Most personal injury attorneys offer free consultations and work on a contingency fee basis.
How Contingency Fees Typically Work
While specifics vary by firm and state, common features include:
- No upfront attorney fee.
- Attorney receives an agreed percentage of the settlement or verdict.
- If there is no recovery, the attorney’s fee is generally zero, but you may be responsible for certain case costs depending on your agreement.
Ask the attorney to explain:
- The percentage at different stages (pre‑lawsuit vs. litigation vs. trial).
- How case costs are handled and when they are deducted.
- How medical liens or unpaid bills will be addressed from any settlement.
Get the fee agreement in writing and keep a copy.
Mistakes That Can Hurt Your Car Accident Injury Claim
Avoid these common pitfalls:
- Talking about your case on social media – Photos or posts can be taken out of context.
- Skipping medical appointments – Creates gaps that insurers use to argue you recovered or weren’t really hurt.
- Failing to tell your doctor the full story – If medical records downplay your pain or omit limitations, your claim may be undervalued.
- Signing documents you don’t understand – Especially releases or broad authorizations.
- Waiting too long to get legal help – Evidence disappears, witnesses move, and deadlines approach.
What a Lawyer Can Actually Do for You
A personal injury attorney may:
- Investigate the crash and gather evidence (photos, video, witness statements).
- Analyze insurance coverage and identify all potential sources of recovery.
- Coordinate with your medical providers to obtain complete records and bills.
- Calculate and present your medical, wage, and pain‑and‑suffering damages.
- Handle negotiations with insurers and defense attorneys.
- File and manage a lawsuit if settlement is not reasonable.
An early consultation can clarify whether you’re better off handling things on your own or having representation.
Practical Next Steps After a Car Accident
- Prioritize your health: complete your treatment plan.
- Organize your paperwork: reports, medical records, bills, and wage information.
- Stay cautious with insurers: be honest but concise; avoid speculation.
- Document your recovery: keep a simple journal of pain, activities, and missed work.
- Contact a licensed car accident attorney in your state for a case evaluation and to understand your legal options.
This guide is meant to help you navigate the process more confidently, but it cannot replace personalized legal advice. A qualified attorney can review your specific facts, explain your rights under your state’s law, and help you pursue the compensation you may be entitled to.