If you were hurt because someone else was careless—whether in a car crash, a fall, a dog bite, or another incident—you may have a personal injury claim. For most people, this is a confusing and stressful process that unfolds while they are still in pain and worried about bills.
Understanding Personal Injury in Everyday Terms
This guide explains the typical path of a U.S. personal injury claim, what you can expect, and how to protect yourself. It is general information only and not legal advice. Laws vary by state and situation, so it is important to speak with a licensed attorney in your state about your specific case.
The Legal Basics: Fault, Negligence, and Damages
Most personal injury cases are based on negligence. In plain language, that means:
- Someone had a duty to act with reasonable care (for example, a driver following traffic laws, a store checking for hazards).
- They breached that duty (speeding, texting while driving, ignoring a spill on the floor).
- That breach caused your injury (the crash or fall actually led to your harm).
- You suffered damages (medical bills, lost wages, pain, etc.).
Types of Damages You May Claim
Common categories include:
- Medical expenses – ER visit, hospital care, surgery, physical therapy, medication, medical equipment.
- Future medical care – ongoing treatment, rehab, or future procedures.
- Lost wages – income you missed because you couldn’t work.
- Reduced earning capacity – if your injuries affect your long‑term ability to work.
- Property damage – vehicle repairs, destroyed personal items, etc.
- Pain and suffering – physical pain, emotional distress, loss of enjoyment of life.
The value of these damages depends on your injuries, medical treatment, insurance limits, and the law in your state.
Step‑by‑Step: What Usually Happens After an Injury
Step 1: Immediate Aftermath (First Hours and Days)
Your priorities:
- Get medical care right away, even if you feel “okay.” Some serious injuries show up later.
- Call 911 if necessary and obtain a police or incident report.
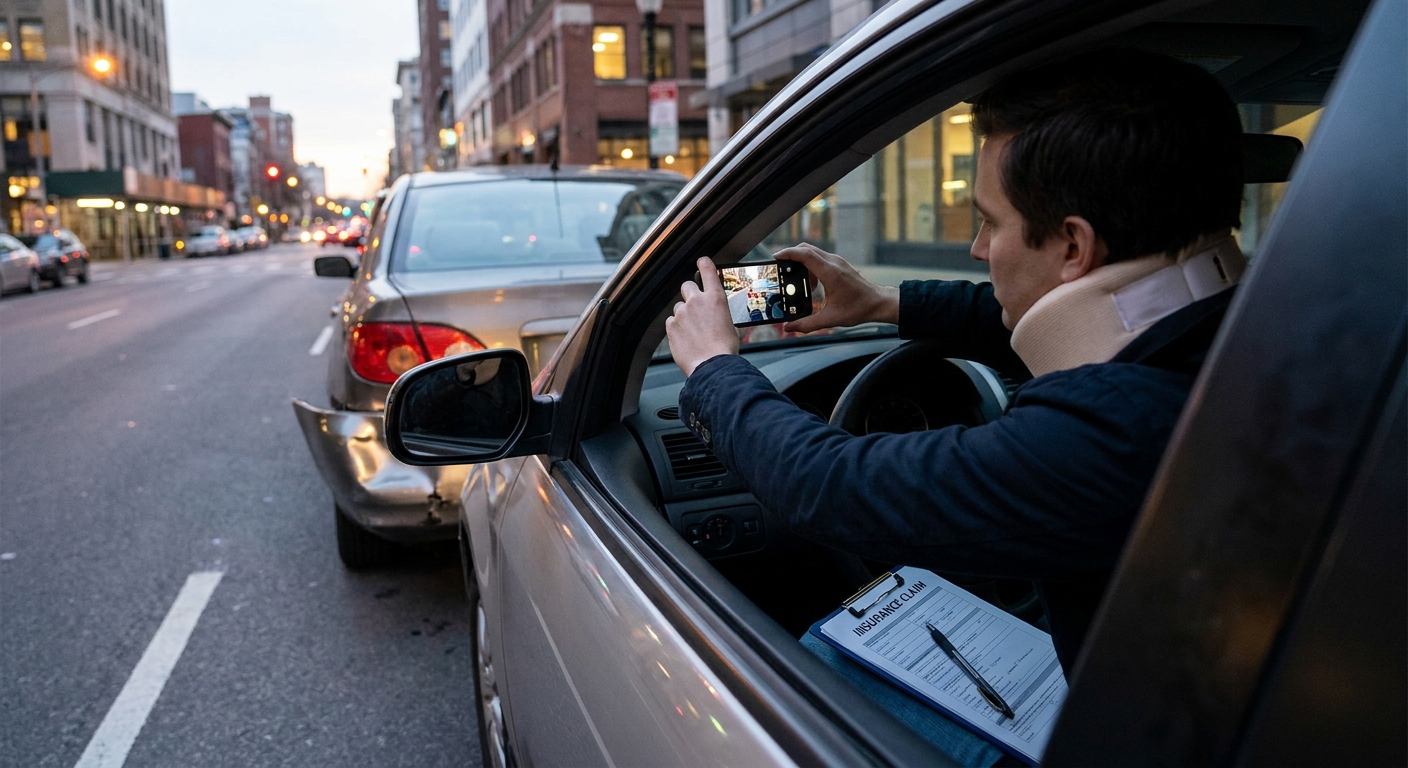
- Document the scene if you are able: photos of vehicles, injuries, conditions (ice, spill, broken steps).
- Collect information: names, addresses, phone numbers, insurance details, witness contact info.
Checklist: First 72 Hours
- [ ] Emergency/urgent care visit
- [ ] Police or incident report number
- [ ] Photos/videos of scene and injuries
- [ ] Contact information for witnesses
- [ ] Notify your own auto or homeowner’s insurer (if applicable)
Step 2: Ongoing Medical Treatment (Weeks to Months)
- Follow your doctor’s instructions and attend all appointments.
- Keep a symptom journal: pain levels, limits on daily activities, emotional impact.
- Save all bills, receipts, and records related to your injury.
Insurance companies will look closely at your treatment history. Gaps in care or ignoring medical advice can be used to argue that you were not seriously hurt.
Step 3: Opening and Handling the Insurance Claim
In many cases you’ll deal with at least one insurance company:
- The at‑fault party’s insurer (for liability coverage)
- Your own insurer (for medical payments coverage, uninsured/underinsured motorist, or property damage)
Typical steps:
- Claim is opened – You call the insurer or submit online; you get a claim number.
- Adjuster assigned – This is the person investigating your claim and negotiating payment.
- Information requests – They may ask for medical records, proof of income, photos, and statements.
You are not required to give a recorded statement to the other party’s insurer in most situations; this is a key issue to discuss with a lawyer.
Step 4: Settlement Negotiations
Once you have completed most of your treatment—or understand your long‑term prognosis—your claim is usually valued and negotiated.
- You or your attorney submit a demand package summarizing:
- Facts of the accident
- Medical treatment and bills
- Lost wages
- Impact on your life
- The insurer responds with an offer—often lower than your demand.
- There may be multiple rounds of back‑and‑forth negotiation.
If you reach agreement, you sign a release in exchange for payment. This typically ends your right to seek more money for the same injury, so read carefully and get legal advice if unsure.
Step 5: Filing a Lawsuit (If Needed)
If negotiations stall or the insurer denies your claim, your attorney may file a civil lawsuit.
Typical stages:
- Complaint filed in court; the defendant is served.
- Discovery – exchange of documents, written questions, depositions.
- Motions – legal arguments about what evidence can be used or whether the case should proceed.
- Mediation or settlement conferences – many cases settle before trial.
- Trial – if no settlement, a judge or jury decides.
Lawsuits can take many months to several years depending on complexity and court backlog.
Typical Timelines in a Personal Injury Claim
Every case is different, but many follow a pattern:
- First week–3 months: Emergency care, early treatment, opening claims, property damage resolved.
- 3–12 months: Ongoing treatment, physical therapy, follow‑ups, diagnostic tests.
- 6–18 months: Once treatment stabilizes, demand package and negotiations.
- 1–3+ years (if suit filed): Lawsuit, discovery, potential trial.
Statutes of limitation (deadlines to file a lawsuit) vary sharply by state and claim type. Missing this deadline can permanently bar your claim. This is a major reason to speak with an attorney early.
Costs, Fees, and Typical Settlement Ranges
Out‑of‑Pocket Costs
You may face:
- Health insurance copays/deductibles
- Uncovered medical care (chiropractic, specialty treatments, etc.)
- Transportation to treatment
- Over‑the‑counter medications or medical equipment
Sometimes these are reimbursed in a settlement, but there is no guarantee.
Contingency Fees: How Injury Lawyers Usually Get Paid
Most U.S. personal injury attorneys work on a contingency fee basis:
- You usually pay no upfront attorney fee.
- The lawyer takes a percentage of the settlement or verdict if you win.
- If you recover nothing, the attorney’s fee is usually zero, but you may still owe some case costs (court filing fees, records, expert reports) depending on your agreement.
Common contingency fees (exact percentages vary by state, firm, and stage of the case):
- A set percentage if the case settles before a lawsuit is filed
- A higher percentage if the case goes into litigation or proceeds to trial
Always read and ask questions about the fee agreement before signing.
Settlement Amounts: Why They Vary So Much
Personal injury settlements can range from very small to very large. Factors that often affect value:
- Severity and permanence of injuries
- Amount of medical treatment and bills
- Length of recovery and time off work
- Whether fault is clear or disputed
- Available insurance coverage and policy limits
- How injuries affect your daily life and future
Because every case is unique and many details matter, it is not reliable to assume your claim is “worth” what someone else received. For a realistic range, speak with a licensed attorney who has handled similar cases where you live.
Documents and Evidence to Gather
Strong documentation can significantly improve your claim.
Core Documents
- [ ] Police report or incident report
- [ ] Photos/videos of the scene and your injuries
- [ ] All medical records related to the injury
- [ ] All medical bills and receipts
- [ ] Health insurance explanation of benefits (EOBs)
- [ ] Pay stubs or proof of income (if claiming lost wages)
- [ ] Repair estimates or invoices for property damage
Helpful Extras
- [ ] Symptom and pain journal
- [ ] List of medications
- [ ] Calendar of missed work days or limited duties
- [ ] Statements or contact info from witnesses
Keep everything in one folder—paper or digital—so you can easily share it with your attorney or the insurer when needed.
Common Mistakes That Weaken a Personal Injury Claim
Avoiding a few key errors can help protect your rights.
- Delaying medical care – Waiting weeks to see a doctor lets insurers argue you were not seriously injured or that something else caused your pain.
- Ignoring doctor’s orders – Skipping appointments, not taking prescribed medication, or stopping treatment early can lower the perceived seriousness of your injuries.
- Oversharing on social media – Posts, photos, or check‑ins can be used out of context to suggest you are less injured than claimed.
- Giving recorded statements without advice – You may say something under pressure that is later used against you.
- Accepting the first quick offer – Early offers are often low and may not cover future treatment or lost earning capacity.
- Missing legal deadlines – Waiting too long to act can permanently bar your claim under your state’s statute of limitations.
When It Makes Sense to Talk to a Lawyer
You are allowed to handle a claim yourself, but consulting a lawyer is often sensible when:
- You suffered moderate or serious injuries (fractures, surgery, long‑term pain).
- You missed significant time from work or cannot return to your old job.
- The other side is blaming you for the incident.
- More than one party may be at fault (multiple vehicles, a company and an employee, etc.).
- The insurer has denied your claim or made a very low offer.
- A commercial vehicle, government agency, or business property is involved.
Most personal injury attorneys offer free initial consultations. This is a safe way to understand your options and the value of your case before making decisions.
Practical Next Steps If You’ve Been Injured
- Get medical care immediately and follow up as recommended.
- Report the incident (police report, store incident report, employer report).
- Gather evidence: photos, contact information, and documents.
- Notify insurers, but be cautious about recorded statements and broad medical authorizations.
- Track your damages: medical bills, lost wages, out‑of‑pocket costs.
- Consult a licensed personal injury attorney in your state to review deadlines, liability issues, and settlement strategy.
This overview cannot cover every situation, and it is not a substitute for personalized legal advice. A qualified attorney can analyze your specific facts, explain your rights under your state’s law, and help you make informed decisions about your claim.